Tuesday, December 11, 2018

January 2019 Position

Here is an overview of my January 2019 position:

November 23: I put on my M3 on Friday, 56 DTE like all positions. Since the market was at 1488, I placed my butterflies at 1460. Because of market pricing,  I had to buy 24 butterflies instead of 10 to have a Delta value of -100. In order to offset the negative Delta, I bought a 1270 call to bring the total Delta to -5.

The risk profile graph of the initial position can be seen below:


November 29: The following Thursday, the negative Delta of the position exceeded -50, so I added two 1480/1500 verticals to make the Delta more positive. Adding the two verticals also helped flatten out the t + 0 line and moved some of the risk from the front to the back of the tent of the butterflies. With the adjustment, the Greeks are as follows: Delta -26, Theta 79, and Vega -234.

December 3: I had to move my position up the following Monday because the market was 30 points above my long strikes. I had refrained from moving them up earlier because my Vega was still negative, but because my Theta was so low I moved the butterflies up to 1510. This is was 35 points below the current market price. When moving my butterflies up, I sold two butterflies because my Delta exceeded -50 with the adjusted position. The Greeks for the updated position are Delta -42, Theta 147, and Vega -649.

The risk profile graph of the adjusted position can be seen below:


December 4: I had to move my butterflies again the next day because the market had dropped so much over the past few days (it was below my shorts) and the Delta was above the positive 50 limit for the position. I placed the new butterflies at 1450, a little more than 30 points below the market at 1483. The Greeks for the updated position are Delta -18, Theta 141, and Vega -522.

The risk profile graph of the position can be seen below:


December 10: I had to move my butterflies even further down because the Delta of the position exceeded 50 after the market had moved down more. I moved the butterflies from 1450 to 1420, about 20 points below the market. The Greeks for the updated position are Delta 9, Theta 151, and Vega -483.

The risk profile graph of the position can be seen below:


I will try and update as often as possible in the new year. I hope you continue to follow the blog as I close the January position and continue trading in 2019!


Thursday, August 9, 2018

June and July 2018 M3 Positions

Below you can find my June and July M3 positions. Because the June position did not require any adjustments, I decided to include the July trade in this post as well.

June

April 20: I started the position 56 DTE. Since the market was at 1562, I put my butterfly at 1540 which is about 20 points below. I had to enter 15 butterflies instead of 10 because only 10 butterflies did not give me enough negative Delta to buy a deep-in-the-money call. After buying 15 butterflies and the call, I also bought three 1510/1530 verticals so that my position Delta came to -6.4. I started the trade with values of -660 for Vega and 76 for Theta.

Below is a risk profile graph of my starting June position.


May 2: I decided to take the position off for a $3,575 profit. Since my profit/loss is about +/- $3,000, this profit made sense to take, especially since it did not require any adjustments.

Below is a risk profile graph of the position when I closed it.


July

May 25: I started the position at 56 DTE for July. When I bought 10 butterflies at 1600 for this expiration, I had too much negative Delta, so along with the call at a strike of 1400, I also bought three 1560/1570 vertical spreads. These allowed my overall position Delta to be -6, increased the starting Theta of the position (49.6), and made my Vega value more negative (-504).

Below is a risk profile graph of the starting position.


June 5: After the market rose to 1660, it was higher than the upper strike of the butterfly, and I decided to move all 10 butterflies up to 1630. I placed them 30 points below the market because I thought after rising so rapidly, the market would likely come back down and would sit in the tent of the butterfly, where I could make the most money.

June 7: Just two days later, I had to make another adjustment to the position. The negative Delta was too high (more than the limit of -50 in the tent) and I had to add verticals to correct it. I put on five 1610/1620 verticals which brought the Delta down to -36.

Below is a risk profile graph of the position after the previous adjustments.


June 11: The negative Delta of the position was too high again, so I bought more verticals to correct it. I put on five verticals at 1620/1640 to bring the Delta down to -31.

June 18: One week later, I had to move up all of my butterflies again because the market was above the upper strike of the butterfly. I moved the butterflies to 1660 since the market was at 1689. With this move, the Delta of the position was too negative, so added five additional verticals at 1640/1660 to correct the Delta. The position is currently down $835.

Below is a risk profile graph of the position after the previous adjustments.


June 22: By the end of the week, the position was at -$2,500, so I decided to close it before the position greatly exceeded my max loss. The position ended with values of 12.5 for Delta, 200 for Theta, and -852 for Vega.

Thank you for reading! If you have any questions or concerns, feel free to leave a comment and I will get back to you.

Thursday, December 21, 2017

January 2018 Expiration M3


Hello everyone. Below I would like to share my January expiration M3 position.

November 24th: On Friday, 56 DTE like all the positions I put on, I started my position. Since the market was at 1519, I centered my butterflies at 1490. This is because of the guideline with M3 positions that the butterflies should be placed 20-30 points below the market. The butterflies had 50-point wingspans as usual. In order to offset the negative Delta, I bought a 1450 call.


The risk profile graph of the beginning position can be seen below:


November 29th: After five days in the position, the market had come up almost 25 points and was level with the upper wing of the butterfly. Also, the Vega was almost positive and the Theta was very low. To correct this, I moved half of the butterflies up to the 1510 strike price. Doing this allowed me to have a higher negative Vega value and brought the tent of my butterflies closer to the market.

The risk profile graph of the updated position can be seen below:


December 6th: Within a week, the market had reversed and came all the way down to 1509, even lower than when the position was put on. Although the Theta and Vega values were within their limits, the Delta had become greatly positive. To fix this, I moved my butterflies back to 1490. At this time, the positive was up $625.

December 11th: A few days later, with the market at 1520, the Delta of the position was greater (more negative) than -50. To combat this, I added a four 1490/1510 verticals. I did not need four verticals to correct the Delta value; however, I wanted the t + 0 line to be as flat as possible in front of the tent.

The risk profile graph of the updated position can be seen below:


December 14/15th: On the 14th, the Delta of the position was again too positive, so I took off one of the verticals I had previously placed. This corrected the Delta and brought the Delta value close to 0. On the 15th, after the market rallied almost 25 points in one day, the t + 0 line became very uneven and the Delta value became very negative (though not -50). To fix the t + 0 line, I added two additional 1490/1510 verticals (there are now 5). 

The risk profile graph after both updates can be seen below:


December 18th: The market had rallied to almost 1550, and the Theta and Vega values were very low. Also, the market was about ten points above the upper wing. To correct this, I had to move all of the butterflies up to 1520. This allowed me to have a Theta value of 130 and a Vega value of -626. 

The risk profile graph of the updated position can be seen below:


December 19th: I took the position off for a $1,117 profit. 

Monday, November 6, 2017

December Expiration M3

Hello everyone. Below I would like to share my December expiration M3 position as I have traded it so far.

October 20th: On Friday, 56 DTE like all the positions I put on, I started my position. Since the market was at 1509, I centered my butterflies at 1480. This is because of the guideline with M3 positions that the butterflies should be placed 20-30 points below the market. The butterflies had 50-point wingspans as usual. In order to offset the negative Delta, I bought a 1270 call. This call wasn't enough, however, and I bought a 1470/1480 vertical to bring the total Delta of the position to -5.

The risk profile graph of the beginning position can be seen below:


October 25th: After five days in the position, the Delta of the position became +28, and since the limit for positive Delta is 20, I had to adjust the position to bring it below 20. In order to do this, I moved half of my butterflies to 1460, 20 points below the original half at 1480. This adjustment brought the Delta of the position down to 11 and did not significantly affect the position's Theta or Vega values. If I had tried selling my vertical in order to correct the positive Delta, it would not have worked.

The risk profile graph of the first adjusted position can be seen below:


November 6th: Although all of my Greek values were within limits today, I chose to add a vertical at 1470/1490 in order to flatten my t + 0 line. This is something I often do when I trade the M3 because it flattens the profit (and therefore the risk) throughout the front portion of the curve which usually sags as time passes. Also, since the market has been relatively bullish over the past few months, having that extra protection in the front part of the position is reassuring. The position is currently profiting with $1590.

The risk profile graph of the second adjustment can be seen below:


Stay posted for updates on the December position!

Monday, July 24, 2017

August Expiration M3

Hi everyone, below I would like to share my August expiration M3 position.


June 23rd: I put on the position at 56 days to expiration as recommended for the position. Since the market was at 1415, I centered the butterflies at 1390 with 50-point wingspans as usual. I bought a 1280 call to offset the negative Delta which resulted in the position starting with -4.5 Delta.

Below is the risk profile graph of the starting position:


June 28th: Today, because of the massive upswing of the market (more than 20 points), I had to move half of my butterflies up to 1410. With this adjustment, I was able to increase the Theta value and decrease the Vega value of the position, as well as make the Delta less negative. The position is currently down $242.

July 6th: The large upswing from the last adjustment was matched by a downswing of almost 20 points in the market today. As a result, I moved all of my previously adjusted butterflies (at 1410) back to their original position of 1390. Although this move wasn't particularly beneficial to the Greek values of the position, it allowed for greater coverage of the market inside the tent of the butterfly. The position is currently profitable at $338.

Below is the risk profile graph of the position on July 6th:


July 10th: As a result of a 7-point drop, I had to add two 1380/1390 verticals. The Delta value of the position was approaching the negative limit of -50 so the verticals brought some positive Delta to offset that. The addition also increased the Theta value and decreased the Vega value of the position. The position is currently profitable at $1,126.

July 12th: After two days and a total of 15 points up for the market, the negative Delta value rose to -67, which is higher than the limit. This caused the addition of 3 1390/1410 verticals. Although I didn't necessarily need to add all three of the verticals to return the position back to within the limits, I wanted the flatten out the t + 0 line in front of the tent. This could be beneficial in the future since the market has been almost constantly bullish. The position is currently profitable at $925.

July 14th: After two more days of the upward market movement, the Delta was more negative than I wanted again. I ended up adding three 1410/1420 verticals to fix this. This adjustment also helped me flatten out the t + 0 line of my position. Flattening out the t + 0 line is essentially moving the risk to the back end of the butterfly from the front end. By adding these verticals, you can actually see the form of the butterfly shift and the line made from the call actually moves up and starts coming towards the $0 line.

Below is the risk profile graph of the position on the 14th. Notice how the position is shaped differently than the last profile in the post.


July 17th: I added one 1390/1420 vertical because the negative Delta of the position has exceeded -50 again. This adjustment brought the total Delta value to -36.5 and increased the Theta of the position.

July 18th: I added another 1390/1420 vertical to increase the Theta value and continue to flatten the t + 0 line. The Delta had not exceeded the negative limit, but this adjustment made the value less negative (keeping it in check).

Below is the risk profile graph of the position on July 18th. Notice how the call portion of the position has risen even more because of the verticals added over the past two days.


July 20th: Today, because of the 15 point move of from the market over the past two days, I decided to move half of my butterflies up to 1410. The market was outside of the tent (a little too much for comfort) and the Theta of the position was also low. After this adjustment, the negative Delta was beyond its -50 limit, so I added another 1390/1420 vertical to correct it. The position is profitable at $827.

Below is the risk profile graph of the position on July 20th:


July 24th: Today, I added another two 1390/1420 verticals because of the Delta value of -75 (outside of limits). This adjustment increased the Theta and decreased the Vega values of the position. The position is currently profitable at $1,563.

Below is the risk profile graph of the position on July 24th:


Stay posted to see what happens to my August position!

Sunday, April 2, 2017

Weekly Update: May Position


After taking off the March and April positions, I decided to wait until May was 56 DTE before putting on another position. The May expiration options reached 56 DTE last Friday.

3/24 - I put on 15 butterflies at 1330 because having just 10 butterflies didn't generate enough negative Delta to buy a deep in the money call. I decided that this would give me more flexibility throughout the position and allowed me to buy a call at 1220. The Greeks of the positions are Delta value of -5.3, Theta value of 89, and Vega value of -548.

The risk profile graph of position can be seen below:


3/28 - Even though I was only in the position for four days, I decided to take the position off with a $1224 profit (generally, if I hit a +$1000 profit within the first week I take it off). The Greeks of the position are Delta value of -42, Theta value of 77, and Vega value of -468.

The risk profile graph of the position can be seen below:


3/29 - Since there were still 51 DTE for May, I decided to put on a new position for same expiration. I bought 12 butterflies at 1340 (again it was better to buy more than 10 to get a suitable call), a call at 1240 and a 1330/1350 vertical. The position has the following Greeks: Delta value of -4.81, Theta value of 78, and Vega value of -452.

The risk profile graph of the new position can be seen below:


Stay tuned for updates about the May position!


Sunday, March 12, 2017

Weekly Update: Closing March and April M3's


These past two weeks have been exciting for the two positions I have currently been in. I have adjusted and closed both the March and April M3's, so you can find the details below.

March:

Wednesday, March 1: The Vega value of the position went positive after a massive, 26-point rally. To correct this value, I moved five butterflies up to 1370. I also had to add five 1420/1400 verticals to reduce the negative Delta that the moved butterflies had caused. With all of the adjustments for the day, the Greeks are: Delta value of -38, Theta value of 140, and Vega of -157.

The risk profile graph of the position after the adjustment can be seen below:


Friday, March 3: I decided to close the position at 14 DTE because the Gamma value was getting too high and I was profitable for one of the first times in the position. The closing Greeks were: Delta value of -69, Theta value of 293.5, and Vega of -452.7. I closed the position at a $1,396 profit.

The final risk profile graph of the March position can be seen below:


April:

Wednesday, March 8: The Russell 2000 was down eight points and the butterflies were only six points below the current market position. The Delta value of the position was too positive at 20.53, so I had to move seven butterflies up to 1390 in order to offset the Delta. The position now has a Delta value of 2.34, a Theta value of 112.1, and a Vega value of -656.7.

The risk profile graph of the position after the adjustment can be seen below:


Friday, March 10: The Russell 2000 was finally up a few points after being down all week. I decided to close my position for a $2,567 profit. The final Greeks were: Delta value of -1, Theta value of 131, and Vega value of -745.

The final risk profile graph of the position can be seen below:


Stay tuned as I put on my May position in the coming weeks!


Sunday, February 26, 2017

Weekly Update: March and April M3's

This week was a relatively uneventful week for me in relation to my March M3. The only adjustment I had to make was on Tuesday, February 21st because the Vega value of the position was only at -5. I moved half of my butterflies up from 1350 to 1370 as well as added two 1380/1390 verticals to get the position to an adequate Greeks level. The Delta value after the adjustments was -37.6, the Vega was -309.5, and the Theta was 122.2.

The risk profile graph after the adjustment can be seen below:


On Friday of this week, I put on my April M3 since it is now 56 days to expiration. Even though the market was at 1394, I decided to put on 12 butterflies at 1360 because I wasn't getting a high enough negative Delta value that the call I would have had to buy would not have been deep in the money. So, the butterflies bought at this level gave me -95 Delta and allowed me to buy a 1270 call. This also gives me the ability to reduce the butterflies I have in the position instead of buying verticals.

The risk profile graph of the April M3 can be seen below:


Stay tuned as I close my March M3 in the coming weeks!

Sunday, February 19, 2017

March Expiration M3

Hello everyone, below you can see how my March expiration M3 is going.

1/20: To start off the position, I put on 12 butterflies at 1320 with 50 point wide wings and a call at 1180 that gave me a total Delta value of -4. I had to add those two extra butterflies to get greater negative delta and vega values so that I could buy a call deeper in the money with a higher positive Delta value. The market was at 1352 when I started the position.

The risk profile for the beginning position can be seen below:

2/9: I bought a 1360/1370 vertical to reduce the negative Delta of the position. The market was outside of the tent of the butterfly and the Delta value needed to be lower than -50.

2/13: Because the market is just constantly moving up, the Vega became positive and the negative Delta value increased to be more than -50. The verticals themselves would not be able to offset the values, so half of the butterflies were moved up to 1350. A 1370/1380 vertical was also added.

The risk profile from 2/13 can be viewed below:

2/14: With yet another day of the market being up, two 1360/1380 verticals are added to offset the negative Delta value.

2/15: The rest of the butterflies were moved up to 1350 to fix the positive Vega value. Also, two more 1360/1380 verticals are added to gain a satisfactory negative Delta value.

2/17: The extra two butterflies were removed from the position to reduce negative Delta from -70 to -36 and increase the negative Vega. The position is currently down -$589 but there are still 28 days until expiration.

The risk profile from 2/17 can be viewed below:


Stay tuned in the coming weeks to watch as I close my March position and put on an April M3!

Tuesday, January 10, 2017

M3 from January Expiration


Hello, everyone. I know I haven't updated my blog in a long time but I am hoping to get back into the swing of things and update as regularly as I can.

The position seen below is an M3 with a January expiration that I had been trading in the past two months.

11/25 - I bought 15 butterflies at 1330. This is different than the usual 10 butterflies that the M3 position suggests but because 10 butterflies were not giving enough negative Delta, I had to buy 15. The call I bought was at 1260 with a positive 81 Delta value to bring overall delta to a little under -5 like the position is supposed to.

This is the risk profile graph at the start of the position:


12/1 - Today, I am closing position with a $1,440 profit. Because I made so much return in only a week, I decided to take the position out but put on another position on the same day because there is still 50 days until expiration for January. This new position has 14 butterflies at 1290 and a call at 1110.

Here is the risk profile graph of the new position:


12/6 - I bought two 1310/1330 verticals even though the Delta value did not exceed -50. Buying these verticals allowed me to raise the t + 0 line that was sagging between the butterfly and call by reducing the elevated t + 0 line in the tent. Doing this gives me less downside protection higher downside risk but because the market has been continuously bullish, it is safer to have less risk in the front of the position.

12/7 - The Vega value of the position became positive after the market moved higher than the upper wing of the butterfly. In order to correct this, I moved entire position to 1340 and added another butterfly to make 15 total and have a position Delta value of -6.

12/16 - I added two 1330/1340 verticals to flatten out t + 0 line (like before). The position is currently at a profit of $1,158.

This is what the risk profile graph from 12/16 looks like:


12/17 - I added two 1310/1350 verticals because the position's Delta value was at -80. Adding these verticals made it -43 which is within the -50 Delta value limit. This also helped flatten the t + 0 line.

12/20 - I added two 1340/1360 verticals to reduce the negative Delta value of the position and flatten the t + 0 line.

12/23 - I added two 1330/1350 verticals to reduce negative Delta value of the position and flatten the t + 0 line.

12/27 - I took position off with a profit of $2,250 and a total profit from January expiration of $3,690.

Here is the risk profile graph from the end of the trade:


Monday, August 15, 2016

Adjusting the September


 After having the September position on for a few weeks, I have had to make a few adjustments:

August 5th: I had to add two of the 1200/1220 verticals in order to reduce the negative Delta of the position. The market was sitting outside of the tent so I had to adjust the position to have less than -50 Delta.


August 8th: The position had too much negative Delta again so I had to add the 1200/1210 vertical in order to correct it. With the addition of this vertical, the positive Theta and the negative Vega both increased. On this date, the position was up $545.

August 12th: With the negative Delta reaching -55, I had to add the 1200/1220 vertical to the position. Adding this vertical reduced the negative Delta of the position from -54 to -40. The position is currently up $441.

The current risk profile graph looks like this:


Stay tuned over the next few weeks as a keep adjusting my September position!


Wednesday, August 3, 2016

Closing the August Position


  Over the past few days, I have made a series of adjustments to my August position. All of the adjustments I have made were as a result of too much negative Delta. On July 27, July 28, and August 1, I added the vertical 1170/1200 to reduce the negative Delta value of the position (they were at -61, -67, and -60 respectively). The market had been outside of the tent for all of these adjustments. I decided to take the position off yesterday, August 2 with a profit of $1,018. With only 16 days left until expiration, I thought that I should take the profit -which has not been over $1,000 for the position- while I could.

The final risk profile graph of the August 2016 position can be seen below:


The September position is currently at a $479 profit and no adjustments have been needed for this position over the past few days. The September position still has 44 days until expiration.

This is what the September position's current risk profile graph looks like:

Tuesday, July 26, 2016

September Position and Updates to August Position


      As I said before, I put on my September position on Friday, July 22 with 56 days until expiration. The butterflies were placed at 1180 with the lower and upper wings at 1130 and 1230 respectively. I then bought a call at 1040 but that was not enough to offset the negative Delta of the butterfly so I added the vertical 1180/1200. Adding the vertical made the total Delta of the position -6 which is close to the ideal -5 starting Delta value for the M3 position. No updates have been necessary to the September position since Friday and the position is currently down $441.

Here is a risk profile graph from Friday:


            Now for the August position. Today, July 26, I moved half of my butterflies up to 1180 because the Vega value of the position was almost positive (only -6) and the market was 10 points above the upper wing. I also had to add the vertical 1180/1200 to reduce the negative Delta of the position from -57 to -45 which also increased the positive Theta and negative Vega. Having all the verticals of the position at 1180/1200 helps reduce the commission cost if this were a live trade. The position is currently down $53 and I see myself taking it down in the coming week since there are only 24 days until expiration.

The current risk profile graph looks like this:


Thursday, July 21, 2016

Updates in the August Position


    With the market climbing significantly higher over the past week and a half, I have made a couple of adjustments to my August position. The first adjustment was on July 11 where the market had made a large move up and my Vega had become positive 80. In order to correct the value, I moved all of my butterflies up to 1160. The next adjustment was adding the verticals 1180/1200 in order to reduce the negative Delta of the position. Before the verticals were added, the value of the Delta was -72 which is -22 more than the allotted -50 Delta value outside the tent. This adjustment was made on July 12 and the Delta of the position is now -48.

This is what the risk profile graph looks after the first two adjustments:


A few days later, on July 15, I added two additional vertical spreads of 1180/1200 in order to reduce the negative Delta value of the position which was -72. With the addition of the verticals, the Delta value of the position became -42.

One July 18, I added two more of the verticals 1180/1200 for the same reason of reducing the negative value of the Delta value of the position. The value went from -57 to -42 and the value of the Vega became more negative as well.

The last adjustment of the week was on July 22 where I added two of the verticals 1180/1200 in order to reduce the negative value of the Delta from -68 to -26. The position is currently down $600.

Here is the current risk profile graph:


Keep reading as I put on my September position this Friday!


Friday, July 8, 2016

Starting the August Position


       Even though there are only 43 days until expiration, I want to put on an August position. With the market at 1150, I put my butterflies at 1120 with the wings at 1170 and 1070. The butterfly had -113 Delta so I had to buy the vertical 1120/1140 along with a call at 970 to offset it. The Delta value is now -7, the Theta value is 94, and the Vega is -361.

Here is the current risk profile graph of the position:


Tuesday, July 5, 2016

Closing the July Position

     
         As you may have heard Brexit occurred two weeks ago and had large effects on the market. For a few days following the announcement, all the markets tanked a few percent every day all over the world. Having a position on at that time was nerve-wracking even though it was only a dummy position. I have many updates to record from the past two weeks that I will share with you below:

June 24th: On this day, I had to move my butterflies down to 1100 from 1120 in order to cope with Brexit repercussions.

June 27th: With the market tanking today, I moved all of my butterflies down to 1060. Now the position is at approximately 30 points below the market and is down about $1,000.


June 28th: Today I added the verticals 1080/1100 as well as moved half of my butterflies to 1080 in order to correct the positive Vega and negative Delta of the position. With the move, the Delta became -30 and the Vega returned to a negative value.

June 29th: I had to move the rest of the 20 butterflies up to 1080 because the Delta value had reached 24 which is a higher value then is what is recommended for the M3 position. Also, the Vega had turned positive again which was corrected with the movement of the butterflies.


June 30th: With yet another move up, I had to move all 20 of the butterflies to 1120 (30 points below the market position of 1150). At this point, the market is closer to the call than it was to the butterflies (before I adjusted them) and the Theta of the position became negative while the Vega of the position became positive. I also had to add the five verticals 1100/1130 because the negative Delta value was too high.

July 1st: The market only moved up 4 points today so it allowed the position to gain a little bit of the positive Theta but since the Gamma was negative and significant, I had to add the verticals 1130/1150 to keep the negative Delta within limits.

July 5th: I finally took the position off today with only ten days until expiration. Even though throughout a majority of the trade I was at a loss, at the end I made a profit of $1,483. I decided to take the position off because the Delta was very high and adjusting it again might risk the profit.

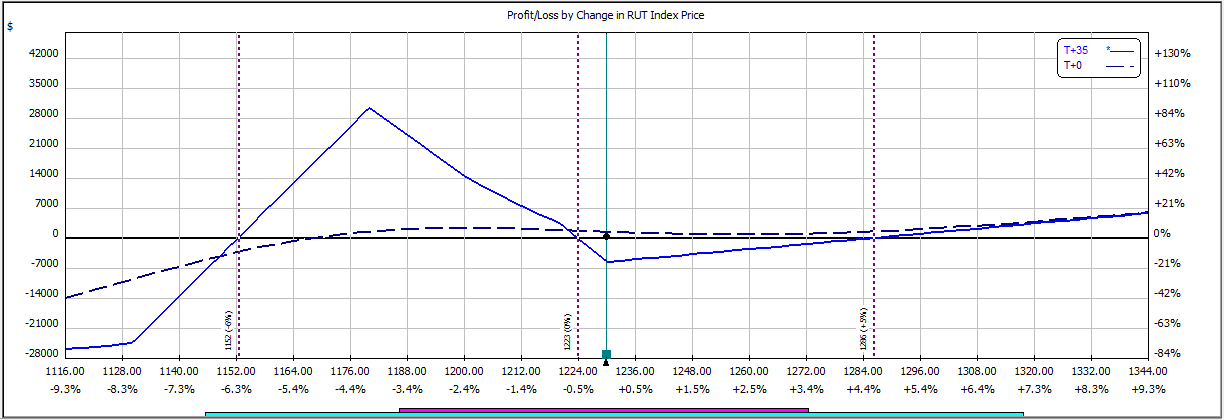
The final risk profile chart for this month can be seen below: